
Message from the President
Accelerated Growth in Fiscal 2024 and Achieved Record High Results
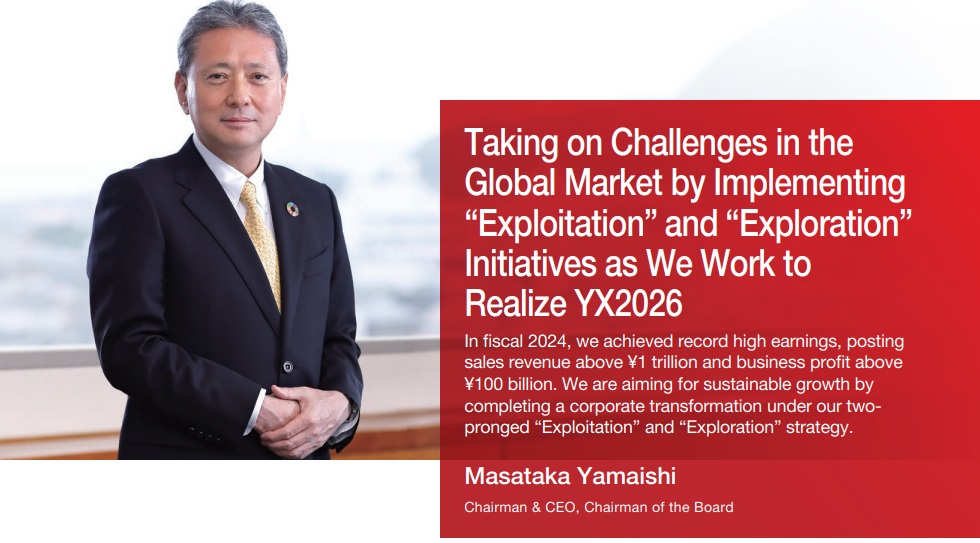
Yokohama Rubber has been around for more than 100 years, and in fiscal 2024, the first year of our current medium-term management plan “Yokohama Transformation 2026 (YX2026)”, the Yokohama Rubber Group achieved record high results, including sales revenue above ¥1 trillion for the first time.
In addition, from fiscal 2022 to fiscal 2024, we achieved record highs in sales revenue and business profit for three straight years. Our tire business achieved the highest sales growth rate among the world’s top 10 tire makers. In addition, we are the only member of the top 10 to achieve significant growth in unit sales of passenger car tires, a category where all the other major tire makers saw their sales volumes decline.
Also, our OHT (off-highway tire) business, which we have built into one of our core strengths, now has the largest share in the global market for agricultural machinery tires and the second largest share for tires used on industrial machinery. In addition, our February 2025 acquisition of The Goodyear Tire & Rubber Company’s OTR (off-the-road tire) business has solidified our No. 3 position in the global market for mining & construction vehicle tires.
These developments have led to Yokohama Rubber being ranked as the world’s fourth strongest tire brand in the “Tyres 25 2025” report from Brand Finance. We believe our growing presence in the global tire market reflects the Yokohama Rubber Group’s expanding tire sales, which is being driven not only by corporate and business acquisitions but also by the organic growth of our existing businesses, and our ability to envision and steadily implement strategies that anticipate changes in the market environment and to respond to challenges from the world’s leading tire makers as well as emerging forces in the market.
Structural Changes in the Global Tire Market
The size of the global tire market is currently estimated to be about ¥20 trillion (at USD/JPY of 110). Consumer passenger car tires account for about half of the total market size, or about ¥10 trillion. In the commercial tire market, truck and bus tires account for ¥6 trillion, and OHT make up the rest of the market.
Chinese tire makers have been rapidly expanding their production capacity in recent years, and they have accounted for about half of the world’s production of truck and bus tires for several years now, turning that segment of the global tire market into a Red Ocean market.
Chinese tire makers also account for one-third of the global production of passenger car tires, and the investment plans of major Chinese tire makers indicate they could account for half of the world’s production of passenger car tires in the near future.
Basic Management Policy and Grand Design for the Tire Business
The Yokohama Rubber Group’s basic management policy is to achieve consistent growth in sales and profits by simultaneously implementing two fundamental approaches: “Exploitation of the strengths of our existing businesses” and “Exploration of opportunities in new markets.” To achieve steady sales and profit growth, we have been implementing a grand design to transform our tire business for more than 10 years.
Back in 2016, before I became president, the global market ratio of consumer tire to commercial tire sales was 1:1. Our tire business was heavily weighted toward consumer tires, with a 4:1 sales ratio, a wide distortion from the overall market composition. We have corrected this distortion through M&A, starting with our acquisition of ATG※1 in 2016, TWS※2 in 2023, and finally Goodyear’s OTR business in February 2025. As a result, our consumer tire to commercial tire sales ratio is now in line with the overall market’s 1:1 ratio.
In addition, the acquired businesses are highly profitable, with each having a profit margin of around 15%. This level of profitability is consistent with our investment discipline. Appropriate post-acquisition investments and management improvements have enabled these businesses to steadily increase their earnings, and we have not needed to post any impairment losses. While our stakeholders have tended to focus on our OHT business acquisitions, the “Hockey Stick Growth” we have achieved in recent years has come more from our existing businesses than acquisitions. In other words, M&A in the OHT market has been just one aspect of our grand design targeting the growth of our tire business as a whole.
In the global tire market, tire makers sell few tires directly to end-user customers. Instead, about 60% of tires sold in the major markets are sold to independent tire dealers. These tire dealers want to purchase many tire types from one tire maker so that they can eliminate the need to place orders with multiple companies and can increase commission fees. The acquisition of Goodyear’s OTR business has made us one of the few tire makers that can supply tire dealers, our main customers, with all types of tires, from passenger car tires to truck/bus tires and OHT. As a result, we now are receiving inquiries from many customers, not only for the newly acquired OHT but also for our passenger car and truck/bus tires. This is putting our overall tire business on an even higher elevated growth trajectory.
I will now explain specific strategies for individual tire products, with “Best Alternative” as a key term.
- 1 ATG refers to the Alliance Tire Group B.V., a Netherlands-based company engaged in the manufacture and sale of tires for agricultural and construction machinery
- 2 TWS refers to Trelleborg Wheel Systems Holding AB, a Sweden-based company engaged in the manufacture and sale of tires for agricultural and industrial machinery
Strengthening Premium Tire Lineup and Cost-Competitiveness
The traditional path to success in the labor- and equipmentintensive tire industry has been to develop economies of scale, but the entry of emerging Chinese tire makers has fundamentally altered this path.
Our response has been to adopt a strategy to enhance profitability by exploiting our existing strengths in the passenger car tire market, and raise the sales ratio of our higher-valueadded ADVAN, GEOLANDAR, and winter tires (AGW) from 40% to 50% within the YOKOHAMA brand, which accounts for 99% of our passenger car tire sales. This strategy takes advantage of one of our core strengths—the technologies that enable us to produce many models of these high-quality and high-performance AGW tires in small lots and supply them as original equipment for premium cars, such as BMW M Series models, Mercedes-AMG vehicles, and various Porsche models.
Most of the tires installed on new premium cars are national (first) brands of Tier 1 tire makers (high-ranking, multi-brand makers) that have second and third brands. As a result, YOKOHAMA brand tires tend to be chosen by car owners when changing their tires, especially after the second time, because our tires are proven to have the same performance and quality characteristics as the Tier 1 maker tires installed on new premium cars while being more affordable than Tier 1 national brands. This is what we call our “Best Alternative by OE leading※3” strategy for consumer tires.
As for standard tires, which account for 50% of our passenger car tire sales, our strategy of exploring opportunities in new markets and responding to the challenge from emerging Chinese tire makers has led to the construction of a new plant in Hangzhou. With the cooperation of local business partners who are providing their knowledge of how Chinese tire makers build plants, we are constructing a plant under our new “1-year plant” concept that will enable us to begin production of prototype tires within one year from the start of construction. This is a strategy that will enable us to quickly start up new plants and realize quick returns on our investments.
By appointing local managers able to use their knowledge of local methods to conduct business operations more efficiently, we are improving the competitiveness of our standard tires.
- 3 OE is short for “Original Equipment” tires supplied to automobile makers for installation on new vehicles.
“Best Alternative” Strategy in Our OHT Business
The OHT market is subdivided into tires for agricultural machinery, mining & construction vehicles, port-use vehicles, and industrial vehicles. The OHT market is more susceptible to economic fluctuations than the passenger car tire market, and the number of tire sizes is high relative to the size of their markets. These market conditions are high barriers to entry, and more than a few major tire makers have withdrawn from the OHT business because they could not withstand the impact from economic fluctuations. As a result, the OHT market has become a Blue Ocean.
Our acquisitions of ATG and TWS have given us the top share in the market for agricultural machinery tires, and our TRELLEBORG, Mitas, ALLIANCE and GALAXY brands have products in all price ranges. By optimizing production for each brand and adjusting the product mix to match demand during different economic conditions, we have been able to maximize profits and our market share.
Turning to the market for mining & construction vehicle tires, the overall market composition is 6:4 in favor of mining vehicle tires. The product mix at Goodyear’s OTR business, which we acquired this year, was more heavily weighted toward mining vehicles, at 7:3. Meanwhile, our OTR business’ mining-to-construction vehicle composition ratio was 4:6. As a result, both businesses had product mixes that were out of line with the overall market composition. However, our acquisition of Goodyear’s OTR business has created an OTR business with a full product lineup that matches the overall market composition ratio of 6:4.
Goodyear’s OTR business was a large business with a wide-ranging product lineup, but it also had high-cost plants in North America and Europe. Moreover, Goodyear did not consider it to be a core business and therefore did not make needed investments. As a result, the business was not profitable. Moving forward, PMI (Post Merger Integration) activities will include necessary revisions to the business’ production allocation and to its production network. We expect these revisions will enhance its cost-competitiveness. In addition, we will be able to use the many Goodyear OTR and TWS sales offices located in the same regions to create a more efficient sales network. The Goodyear OTR acquisition has given us broader product lineup that will enable us to improve production and sales efficiency as we implement a strategy to be the “Best Alternative” to our competitors.
Strengthening the Management Foundation that Will Lead Our Transformation
In 2024, we made a significant change to our top management structure, changing it to a three-person team with a CEO, COO, and Co-COO. One of the major management issues we face is that our efforts to transform our technology and production systems are lagging behind those of other companies. Making the needed improvements is an urgent management issue, so I appointed Shinji Seimiya as President and asked him to assume management responsibility for expediting this transformation. Meanwhile, we need to make our OHT business more resilient to the market’s extremely cyclical nature. I am counting on Nitin Mantri to lead this effort by fully using the businesses and brands that we have acquired to date.
We also have made changes to our Board of Directors. From this year, we reduced the number of Board members to 12 to Management Strategy 15 facilitate more thorough discussions and speed up decision-making. In addition, to strengthen governance, we have increased the ratio of outside directors serving on the Board to 50% and made outside directors the majority of members of the Personnel Remuneration Committee for Corporate Officers and Directors.
Sustainability Initiatives that Contribute to Corporate Growth
Sustainability initiatives are important corporate activities. However, while tackling environmental issues is the right thing to do from global and social perspectives, trying to do everything would place a heavy burden on management. Accordingly, our carbon neutrality initiative is based on efforts that will also reduce costs and contribute to the company’s growth. I think we are moving in the right direction and have made some good progress.
We are expanding our use of renewable and recycled raw materials. For example, we have replaced silica sand with plant-derived silica, and the more plant-derived silica we use the more our silica-related costs go down. We will continue to proactively incorporate new raw materials, and this effort will be aided by technological capabilities that facilitate the search for substitute materials and enable us to monitor suppliers’ production capacity and costs to determine the best time to introduce the new materials.
Regarding our efforts to promote sustainable procurement of natural rubber, our natural rubber processing plant in Thailand is endeavoring to improve the traceability of the natural rubber it uses as a raw material. This effort is being led by plant managers who know and understand local farmers, which makes it possible to prevent deforestation and respect human rights while procuring raw materials at a low cost.
Human Resource Development and Global Strategy Initiatives
I believe that investment in our people is the most effective of the many investments we constantly undertake. We have sponsored about 20 young employees to attend Executive Master of Business Administration (EMBA) programs in Japan to date. To compete in the global market, our staff need to be familiar with common business terms that are used internationally, and I therefore believe we need to raise our global business literacy.
As part of our DX strategy, we are implementing a program to develop DX human resources that will be able to use their acquired know-how at our technology and production sites. Last year, we also conducted an employee engagement survey that aimed to discover how well employees understood our strategy and if it helped motivate them to perform their tasks. The survey revealed some cases where the strategy and the company’s way of thinking were not well understood by staff working at production sites. This is a serious issue that we will seek to resolve by improving our communication with employees. In addition, we will use annual engagement surveys to follow up on outstanding issues. As Yokohama Rubber grows, we want to ensure that employees whose daily efforts are contributing to that growth are appropriately rewarded.
To ensure our strategies are understood and being implemented in all business units, we have been conducting monthly “YX Follow” management reviews since 2017. These reviews check the progress being made in each division and functional unit and are part of a rapid PDCA (Plan-Do-Check-Act) cycle. In addition to checking the progress through these reviews, we will use the wide range of know-how and knowledge gained from acquired companies to complement and strengthen our organization.
Message to Stakeholders
Moving forward, we plan to implement measures that will further solidify our grand design aimed achieving sustainable growth in the years ahead. We hope to make this strategy part of our organizational culture and maintain our current sales and profit growth momentum as long as possible. I consider this to be my main task and a mission that must be fulfilled. I hope that our stakeholders will understand and support our corporate philosophy and activities and look forward to a bright future for the Yokohama Rubber Group.